Selling Your Seattle Home Before Buying in Arizona: Timing, Bridge Options, and Mistakes to Avoid

Selling Your Seattle Home Before Buying in Arizona: Timing, Bridge Options, and Mistakes to Avoid
One of the first questions Seattle homeowners ask us about moving to Arizona is simple: do I sell first, or buy first? There is no single right answer. The best sequence depends on your equity, your income, your timeline, and how quickly homes are selling on each side of the move.
This guide walks through the main options, the tools that can bridge the gap between two closings, and the mistakes we see most often. We handle both sides of Seattle to Arizona moves at Badger Real Estate, so we plan the sale and the purchase together.
Sell First, Buy First, or Overlap the Two?
Redfin's guide to buying and selling at the same time and Zillow's guide to whether to buy or sell first describe the same core trade-offs:
| Approach | Main advantage | Main risk |
| Sell first | Sale proceeds can fund your down payment, and you avoid carrying two mortgages. | You may need temporary housing, and you may have to move twice. |
| Buy first | More time to search, and less pressure to move out quickly. | You need cash or financing for the down payment before your home sells, and a strong debt-to-income ratio to qualify. |
| Contingent offer | You can back out of the purchase if your current home does not sell. | Sellers may find a contingent offer less attractive than a clean one. |
| Rent-back | You stay in your old home for a short time after closing, which can avoid a second move. | The buyer must agree, and it must be planned before you list. |
Why Sell First Often Makes Sense for Seattle Homeowners
For many of our clients, selling first is the cleanest path: you know exactly how much equity you are taking to Arizona, you are not paying two mortgages, and your debt-to-income ratio is simpler when you apply for the next loan. The question is timing.
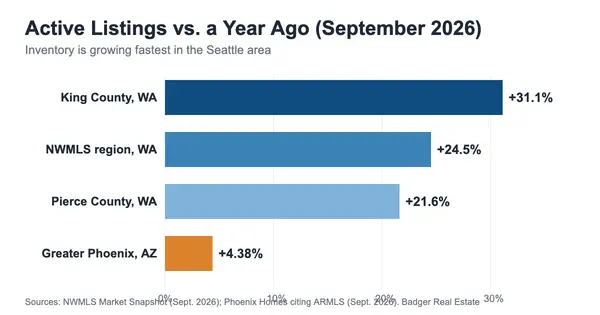
The Seattle market is not as frantic as it once was. According to the Northwest Multiple Listing Service's September 2026 market snapshot, King County active listings were up 31.1% from a year earlier, and buyers signed contracts on about 62 homes for every 100 new listings. Redfin's King County data shows a median of about 28 days on market, with about a quarter of homes seeing a price drop. Well-priced, well-presented homes still sell, but pricing and preparation matter more than they did when inventory was tight. If you are curious how this compares with Arizona, see our buyer market update for Seattle and Arizona.
Tools That Bridge the Gap Between Two Closings
- Home equity line of credit (HELOC). Lets you borrow against your current home's equity for the next down payment. You have to qualify, and it is best arranged before you list, since lenders can be reluctant to open one on a home that is already for sale.
- Bridge loan. A short-term loan that covers a down payment until your home closes. Redfin notes that not every bank offers it and that it can be difficult to qualify. Costs and terms vary a lot by lender, so compare carefully.
- A longer closing on your sale. Zillow suggests asking for a 60-day close on your current home when you accept an offer, so you have more time to find and close on the next one. Whether a buyer will agree depends on the market and the offer.
- Rent-back. Negotiating a few weeks or months of occupancy after closing can give you time to finish buying in Arizona without moving twice or paying for temporary housing.
- A lender who works across both states. Ask a lender early how they would treat your sale proceeds, your existing mortgage, and your income when you apply for the Arizona loan. The Consumer Financial Protection Bureau has a useful guide to shopping for a mortgage and comparing loan estimates.
What Selling in Washington Costs (a Closer Look at Excise Tax)
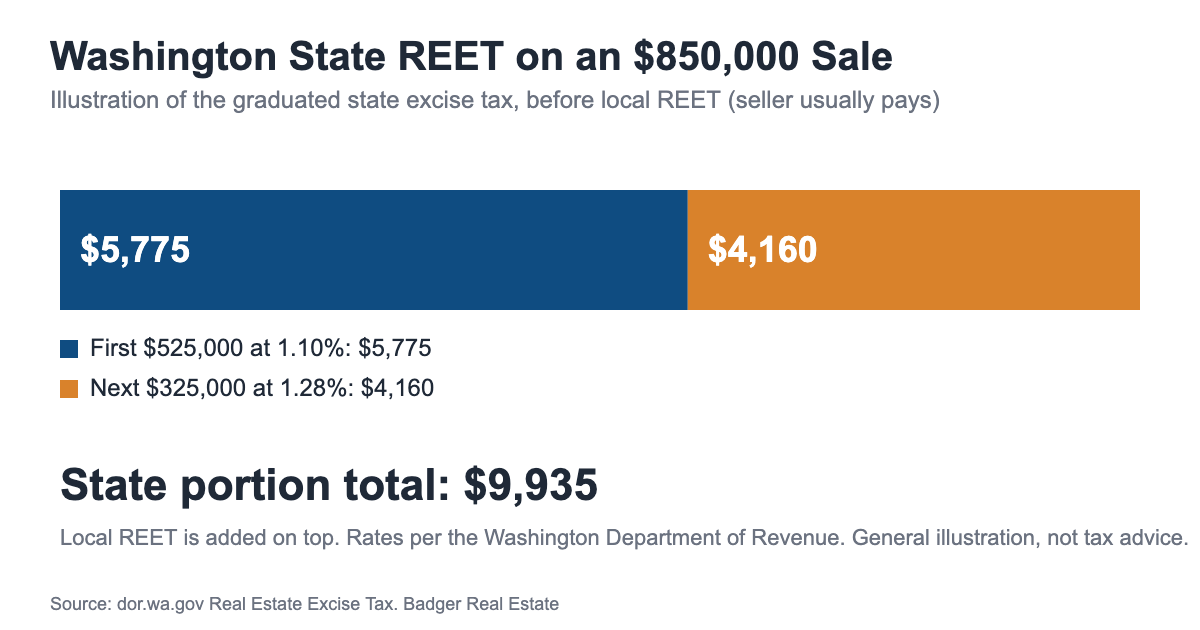
Most sellers think about agent commissions and repairs, but Washington also charges a real estate excise tax (REET). The seller usually pays it. According to the Washington Department of Revenue, the state tax is graduated: 1.10% on the portion of the price up to $525,000, 1.28% from $525,000 to $1,525,000, 2.75% from $1,525,000 to $3,025,000, and 3% above that, with local REET added on top.
As an illustration, on an $850,000 sale the state portion works out to about $9,935 ($5,775 on the first $525,000 plus $4,160 on the next $325,000), before the local add-on. Your actual costs depend on your sale price and location, so ask us for a net sheet before you decide on a price.
Will You Owe Tax on Your Gain?
Many homeowners are surprised to learn how much of their gain may be excludable. According to IRS Topic 701, you may be able to exclude up to $250,000 of gain on the sale of your main home, or up to $500,000 if you are married filing jointly, if you owned and used the home as your main residence for at least two of the five years before the sale. Gain above the exclusion is generally taxable. The IRS explains the rules in detail in Publication 523, Selling Your Home. This is general information, not tax advice. Talk with your CPA before you list, especially if you have owned the home for a long time or have rental history.
Seven Mistakes to Avoid
- Waiting to talk to a lender. Get pre-approved for the Arizona purchase, and ask how your sale will affect that approval, before you list. A stronger credit profile helps, so see our post on how to improve your credit before buying a home in Arizona.
- Overpricing the Seattle home. In a market with more inventory, an overpriced listing sits and takes price cuts. We use appraiser-level analysis to price right the first time.
- Skipping the net sheet. Know your real proceeds after commissions, excise tax, payoff, and repairs before you commit to a buying budget.
- Assuming your closing dates will line up. Closings slip. Build in a cushion, and negotiate a rent-back or longer closing where it helps.
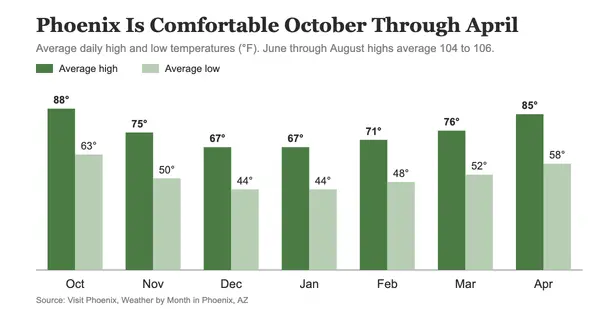
- Buying in Arizona before seeing it in person. The best way to avoid regret is a scouting trip. See why October through April is the best time to scout Arizona homes and which Arizona city is actually right for you.
- Ignoring the tax side. Ask your CPA about the home sale exclusion and any state-specific considerations before you sign a listing agreement.
- Using two unconnected agents. When the Seattle sale and the Arizona purchase are coordinated by one team, the timing, contingencies, and communication are much easier to manage.
A Sample Game Plan
- Meet with us for a free home value and net proceeds estimate on your Seattle-area home.
- Talk with a lender about pre-approval, HELOC or bridge options, and how your income and sale proceeds will be treated.
- Take a scouting trip, tour homes, and narrow your Arizona city. Our Dream Home Questionnaire helps us line up the right tours.
- Prepare and list the Seattle home, negotiating closing date and rent-back terms to match your Arizona timeline.
- Write an offer in Arizona with the right contingencies, then coordinate both closings.
Curious what your equity could buy? See what $500k gets you in Seattle versus Mesa and the biggest changes when moving from Seattle to Arizona.
Frequently Asked Questions
Should I sell my Seattle home before buying in Arizona?
For many homeowners, selling first is the simplest approach because the proceeds can fund the Arizona down payment and you avoid carrying two mortgages. The trade-off is that you may need temporary housing or a rent-back. The right answer depends on your equity, income, and timeline.
What is a bridge loan and do I need one?
A bridge loan is a short-term loan that covers a down payment until your current home sells. Not every lender offers one and it can be difficult to qualify, so many homeowners use a HELOC, a longer closing, or a rent-back instead. Compare costs and terms with your lender.
Can I stay in my home after it sells?
Often, yes, if the buyer agrees to a rent-back. This lets you remain in the home for a short time after closing while you finish buying in Arizona. It should be planned before you list.
Will I owe taxes when I sell my Seattle home?
It depends. Under IRS rules, many homeowners can exclude up to $250,000 of gain, or $500,000 if married filing jointly, if they meet the ownership and use tests. Gain above that may be taxable. Talk with a CPA about your situation.
Can one team help me sell in Seattle and buy in Arizona?
Yes. Badger Real Estate specializes in Seattle to Arizona moves and coordinates both sides of the transaction. Learn more about selling your Seattle home and our Seattle to Arizona relocation service.
Ready to Plan Your Move?
Scott is a certified appraiser with 12,000-plus appraisals completed, so when we tell you what your Seattle home is worth, it is not a guess. Alayna has lived in the Phoenix area for seven years and knows the neighborhoods block by block. Browse Arizona homes for sale and new construction homes, explore Scottsdale, Mesa, Gilbert, and Chandler, or read what past clients say on our reviews page.
Call or text 206-402-8518 for the Seattle area or 480-848-8141 for Arizona, or download our free Arizona Relocation Guide.
#seattlerealestate #arizonarealestate #seattletoarizona #relocatetoarizona #badgerrealestate
This post is general information, not tax, legal, or lending advice. Loan products, taxes, and market conditions vary and change. Consult your CPA, attorney, and lender about your situation. Figures are from the sources below as of the dates noted.
Sources
- Redfin, "How to Sell and Buy a House at the Same Time": Redfin guide
- Zillow, "Do I Buy or Sell a House First?": Zillow guide
- Washington Department of Revenue, Real Estate Excise Tax: Washington DOR
- IRS Topic 701, Sale of your home: IRS Topic 701
- IRS Publication 523, Selling Your Home: IRS Publication 523
- NWMLS Market Snapshot, September 2026: Northwest Multiple Listing Service
- King County housing market: Redfin King County data
- Mortgage shopping guidance: Consumer Financial Protection Bureau
Categories
Recent Posts